

Inside the Bank: A Morning at the Foreign Exchange Counter
At 9:15 on a Tuesday morning, the branch lobby of a state-owned bank in Shanghai is already humming with numbered tickets and soft announcements. Markus, a German production manager at an auto parts company, takes a seat near window No. 7. He has done this once a month for nearly two years, but the ritual still makes him feel like a first-time traveler in a complicated airport.
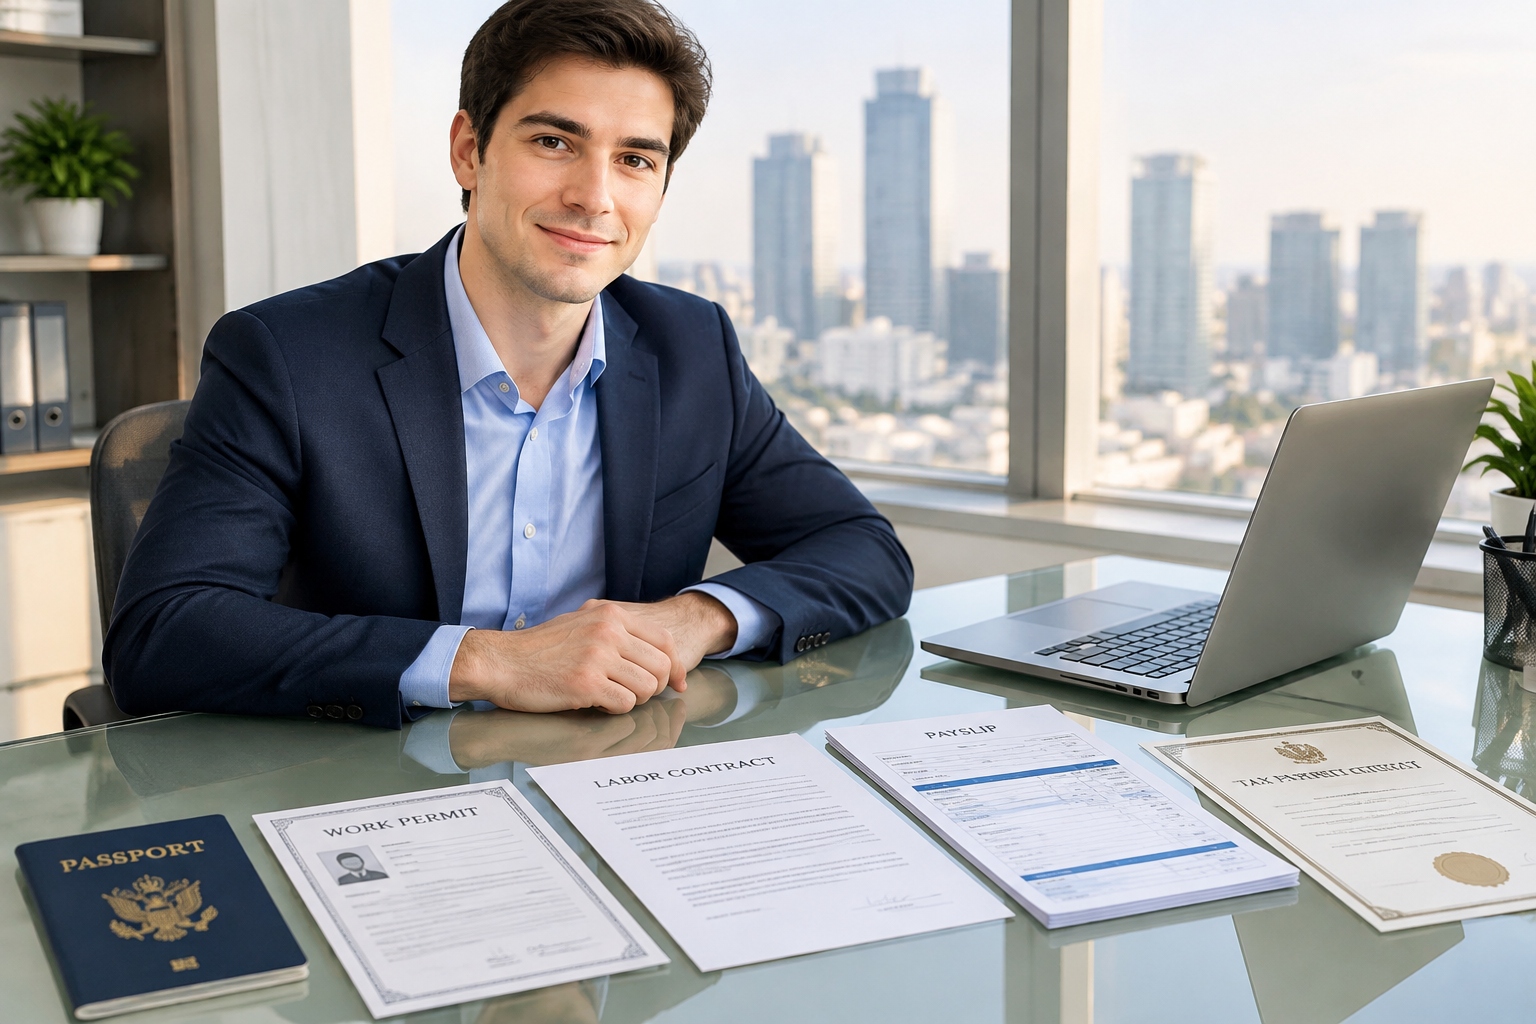
The counter clerk, Ms. Chen, knows him by name. She asks for the same set of documents: his passport, work permit, labor contract, salary slips, and the tax payment certificate that his HR department helped him download from the local tax app the day before. Markus slides them through the slot, and she begins checking each page carefully.
This is not an unusual scene. In cities like Shanghai, Beijing, and Shenzhen, tens of thousands of foreign professionals earn salaries in Chinese yuan and need to send part of that money home. The process, while routine, is governed by rules that many expatriates only learn through trial and error. Here’s what actually happens—and what you need to know before you walk into a bank.
Why Sending Your Salary Is Different from Sending a Gift
China has strict controls on foreign exchange. Under current regulations, every individual is entitled to a convenience quota of up to USD 50,000 per year for that can be used for small remittances without lengthy documentary proof. But salary is a different category. The quota is not a limit on how much you can send if you have legitimate income from working in China. Instead, you can transfer your entire net salary, provided you have the right paperwork to prove the source of funds.
This distinction matters. Many expatriates mistakenly believe that the USD 50,000 cap applies to all remittances. In fact, if your monthly salary is RMB 50,000 (about USD 7,000), you can remit that full amount each month—not just the equivalent of USD 50,000 each year—because it falls under the category of “frequently recurring current account transactions” for employment income.
Three-Part Checklist: What the Bank Wants to See
To process a salary remittance, banks typically require three categories of documents:
Identity and Employment Proof
Your passport with a valid visa and residence permit, plus your foreigner’s work permit or alien employment license. Some banks also ask for a certificate from your employer confirming your current position and salary.
Income and Tax Records
This is the heart of the compliance check. You will need to provide payslips for the last few months (usually the period you are remitting), and a tax payment certificate (shui wu ju yi tuo dan) issued by the tax bureau. In an increasing number of cities, this certificate can be downloaded in digital form from the official tax authority app or website, bearing an official electronic seal. If you file and pay tax through your employer, the HR or payroll department can help you obtain it.
Employment Contract and Supporting Letters
A copy of your valid labor contract is usually requested. If the contract is in Chinese, keep a translation handy. Some banks may also ask for a payment request letter with a statement that the funds are from employment income.
Markus recalls the first time he attempted to send money without the tax certificate. “The counter politely declined, explaining that without proof of tax paid, they couldn’t confirm the money was legitimate salary. I had to go back the next day with the correct paper.”
The Moment of Reporting: Government Paperwork You Don’t Fill Out Yourself
Once the documents are in order, the bank enters the remittance details into a digital system. For any transaction above USD 5,000 (or equivalent in another currency), Chinese banks are required to report the payment to the State Administration of Foreign Exchange (SAFE) under the Individuals’ International Balance of Payments reporting rules.
In practice, the bank staff do the reporting for you. You are not asked to walk to a government office or file a separate declaration. However, you may be asked to fill out a simpler form describing the purpose of the remittance—write “salary” or “personal remittance” in the designated box. The bank obtains your verbal or signed consent, and that’s it.
This behind-the-scenes system catches many first-timers off guard. Some expect to have to file a lengthy self-service form, and others think the bank is being unnecessarily nosy. In fact, the bank is merely complying with reporting obligations that apply to all cross-border transfers above the threshold. The process usually adds only a few minutes to the transaction.
Case Study: Markus Sends His Monthly Salary
Let’s walk through a typical month for Markus, whose net salary is RMB 50,000. He usually holds the remittance until the last working day of the month, after his payslip is issued and his tax is withheld.
- Step 1: He opens the local tax app, navigates to the “Tax Payment Certificate” section, selects the month, and downloads the PDF to his phone.
- Step 2: He prints the PDF at his office or at the bank’s self-service kiosk. Some banks allow electronic documents, but printed copies are safer.
- Step 3: At the bank, he presents his passport, work permit, labor contract, payslip, and the tax certificate. The teller verifies everything against the bank’s internal system.
- Step 4: He fills out a simple remittance application form. Under “transaction purpose,” the teller says, “We will put ‘employment income’ for you.” Markus signs.
- Step 5: The exchange rate is shown on the screen. He confirms. The teller processes the transfer.
Within ten minutes, the money leaves his salary account and is routed to his German bank. The bank charges a fee of about RMB 150 plus a telegraphic transfer fee, which varies. Total cost: roughly RMB 250–300 per wire.
Sometimes, the bank asks a follow-up question during step 4: “What is the source of these funds?” Markus simply replies, “My salary from XYZ Company,” and points to the payslip. For remittances above RMB 50,000 equivalent, a bank officer may also interview the customer as part of a routine anti-money-laundering check. Be patient—it is a standard question, not an accusation.
Watch Out: The “Many Small Transfers” Trap
One temptation for expatriates with more than one income stream—or those who want to avoid asking their boss for extra paperwork—is to split a large remittance into multiple smaller transactions, each under the reporting threshold or under some assumed limit. This is a serious mistake.
Chinese banks now use automated monitoring systems that flag unusual transaction patterns. If you make several transfers to the same overseas account on the same day or over consecutive days, the system will likely freeze your account and ask for supporting documentation. In the worst case, regulators may classify the behavior as deliberately bypassing foreign exchange controls, which can lead to fines, revoked banking privileges, or even legal action.
Markus learned this from a colleague who lost his transfer ability for six months. “He was sending three separate wires of USD 2,000 each because he thought the threshold was USD 5,000. The bank called him in, asked for proof of the source, and eventually required him to sign a statement that he would not split transactions again. It was embarrassing and delayed his rent payment back home.”
Practical Tips for a Smooth Remittance
To avoid these headaches, follow the rules below:
- Keep one main bank account for salary. Do not randomly move funds between several accounts to “confuse” the system.
- Always keep a digital and paper copy of your tax certificates for at least two years.
- Use preferred channels like HSBC, Citi, or Bank of China for faster service, but expect the same checks.
- Some banks allow online fund transfer within China, but the foreign exchange operation must still be done in person or via the bank’s secure messaging system. Check your bank’s policy.
- Set a reminder to send your remittance after the tax authority has issued the certificate (usually one or two days after payroll).
- If your monthly salary is extremely high (above RMB 200,000, for example), expect additional scrutiny from the bank’s compliance department. It helps if your employer provides a formal letter verifying your role and compensation package.
For expatriates working in China, sending money home should feel like a simple monthly ritual—not a minefield. With the right documents and honest reporting, the process is straightforward and fully legal. The key is to treat salary remittance as what it is: a governed cross-border transaction that requires your patience and paperwork, but not your anxiety.
If you have questions about your specific situation, talk to your HR department, or ask your bank’s foreign exchange desk for a “salary remittance” checklist. Many banks even offer bilingual guidance. Following the process correctly also builds a track record that makes future transfers smoother—and that’s a benefit you can carry with you throughout your time in China.
Start the discussion at forum.chinacomes.com