

The Legal Lay of the Land: One Company Law for Everyone
If you have been reading older business guides, you may have seen terms like the ‘Three Capital Laws’ or the ‘Sino-Foreign Equity Joint Venture Law’. Those belong to another era. On 1 January 2020, China’s Foreign Investment Law replaced the three separate laws that once governed foreign-invested companies. That single legal change reshaped what a joint venture is.
Under the current rules, a joint venture in China is not a special creature of statute. It is an ordinary limited liability company, set up and run under the Companies Law of the People’s Republic of China. You register your company the same way a purely domestic private company would. The terms ‘joint venture’ or ‘JV’ remain useful for business, but legally you and your Chinese partner are simply co-shareholders of a Chinese LLC.
Before you start drafting anything, check the National Negative List for Foreign Investment Access, updated every year by the Ministry of Commerce and the National Development and Reform Commission. If your industry is not on the list (and most industries are not), the foreign ownership can be anywhere from zero to 100 percent. If it is on a restricted list, a certain shareholding structure may be mandatory. If it is on the prohibited list, you cannot set up at all. So Daniel’s first question is not ‘What share can I have?’ but ‘Is my industry on the negative list?’
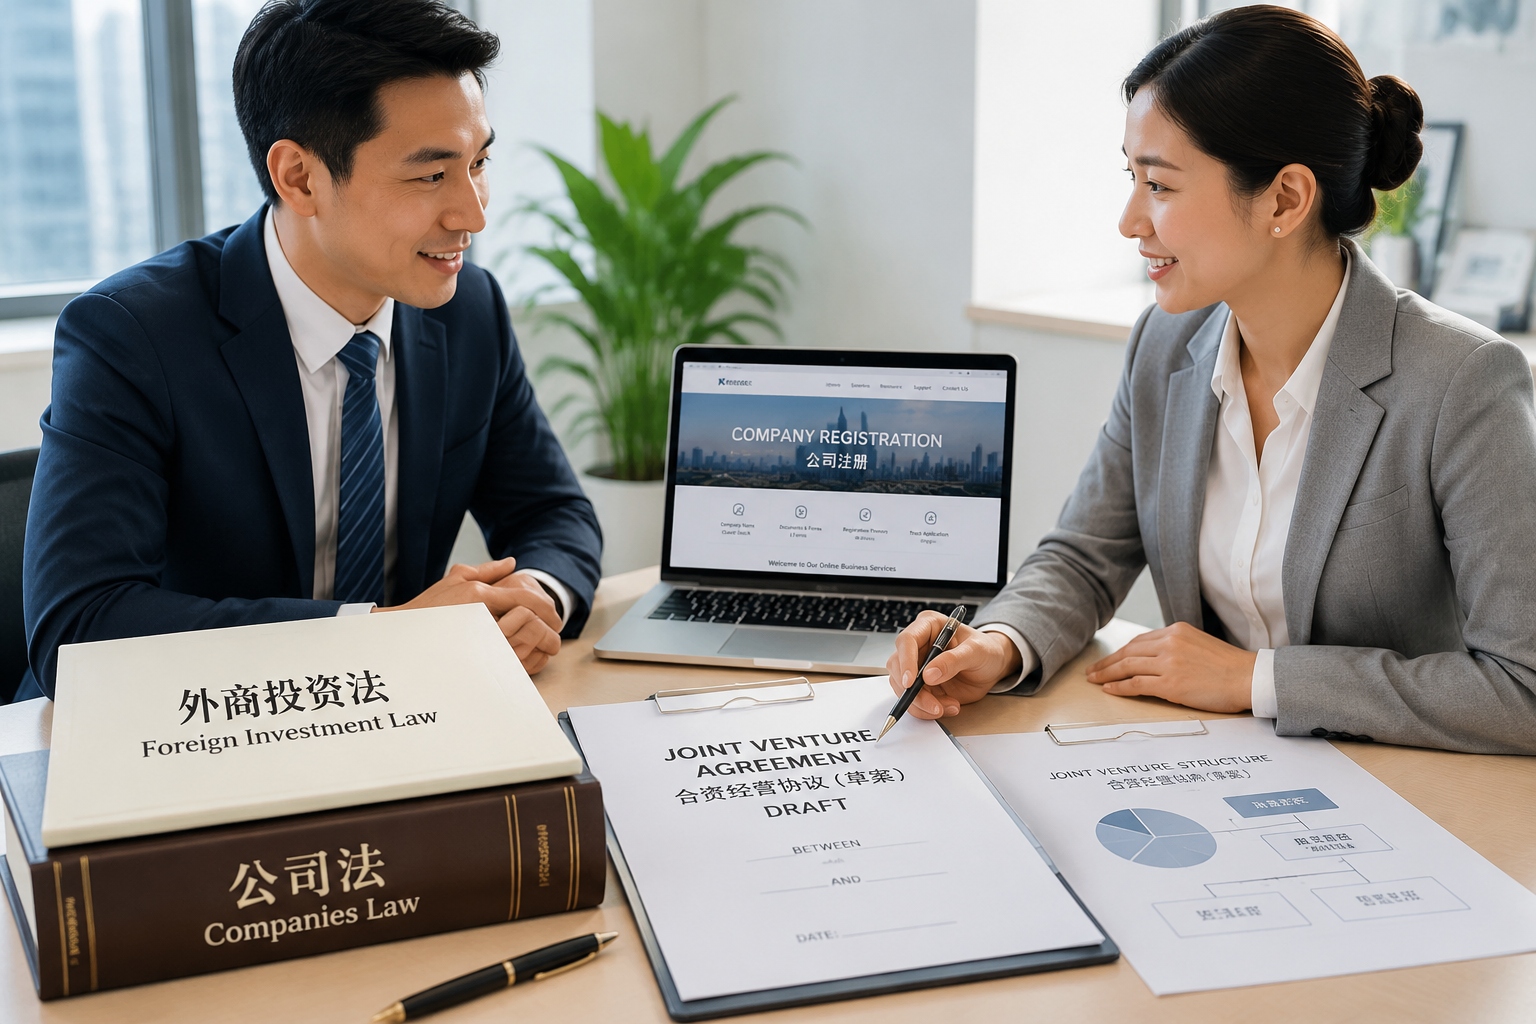
Equity Structure and Board Seats – Designing Control
Once you know the sector is open, your equity ratio becomes a commercial negotiation. Many foreign investors expect that they must give up at least 51 percent ownership to their Chinese partner. That was true in some restricted sectors but is not the default today. In many fields, a wholly foreign-owned enterprise (WFOE) is perfectly legal. A joint venture is then a strategic choice, not a legal requirement.
If you do choose a 50/50 structure, consider what happens when you disagree. A deadlock is possible in any company, but in a 50/50 board deadlocks can freeze the entire operation. Chinese courts will not lightly order a solution beyond the processes in the company charter. A practical way to handle this is with a ‘deadlock-breaking’ clause: set a list of issues that require a supermajority, define how a deadlock is declared, and give one side a right to buy out the other at a pre-agreed valuation method.
Under the current Companies Law, the shareholders’ meeting is the supreme authority. The board of directors is accountable to it. This is a big shift from the pre-2020 joint venture regime, where the board had the final word. If your Chinese partner suggests ‘the board is the boss’, they are probably remembering old habits. Existing joint ventures have had until 31 December 2024 to bring their articles of association in line with the new law; new companies start out that way.
Who Gets Board Seats, and What Can the Board Veto?
Board seats are conventionally allocated by capital ratio, but they do not need to be. You can agree that the foreign partner appoints one more director, or even that some decisions require a director from each side. The same applies to veto rights: certain ‘fundamental’ items – changing the registered capital, approving mergers, approving a large asset transfer – can require, say, a unanimous board vote or at least approval of the director nominated by the minority shareholder. This is where your business lawyer earns their fee, because there is no legal cap on how creative these terms can be, so long as they do not violate mandatory provisions such as shareholders’ statutory rights.
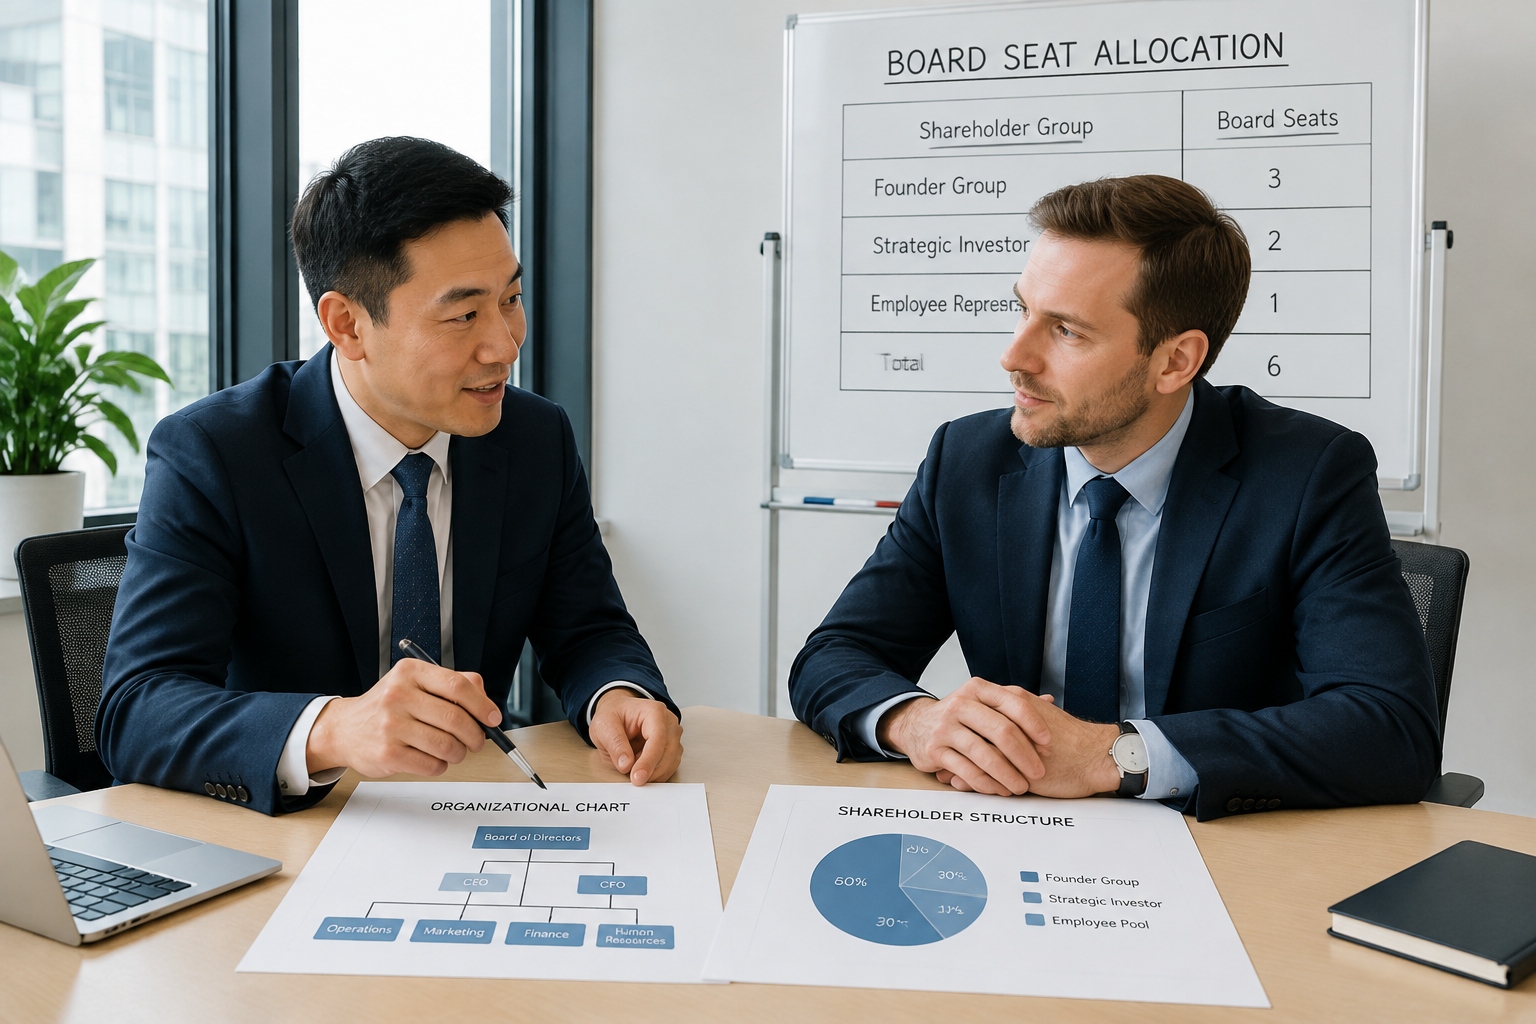
Profit Distribution – From Year-End Accounting to the Bank Account Abroad
Daniel wants to know when the company makes money, how much he can actually use. The legal flow is simple on paper. First, the company pays corporate income tax, normally 25% (smaller firms may enjoy lower rates). After that, it must cover any losses from previous years and set aside a legal reserve of at least 10% of profit after tax until the reserve reaches 50% of the company’s registered capital. Then the shareholders’ meeting can declare a dividend for the remaining amount.
Under the Companies Law, shareholders normally share profits in proportion to their actually paid-in capital. But the law also says all shareholders can unanimously agree not to follow that formula. So you can allocate profits in a different ratio – for example, give the foreign partner a larger share in the first years to compensate for transferred technology. That is lawful, but it must be written into the shareholder agreement or approved by all shareholders in writing before distribution.
Getting the profit out of China is another layer. When the company pays a dividend to a foreign corporate shareholder, it must withhold withholding income tax on that dividend. The general rate is 10%, but under a tax treaty the rate may be lower – for residents of many European countries or the United States it is often 5% if the shareholder owns at least 25% of the company. Your accountant should apply that treaty before the dividend wire.
Practically, you will need a board resolution declaring the dividend, an audit report (or reviewed tax filing), and a payment application to the bank. For amounts above a threshold, the bank will ask for a tax certification form confirming that the withholding tax has been paid. In most stable companies this takes three to seven working days; it is routine, but it involves planning, especially if your home country requires proof of foreign tax credits.
Exit Mechanisms – Selling, Buying Back, or Liquidating
Nobody wants to negotiate an exit while they are negotiating the entry, but the rules of the exit are more important than the percentage on day one.
1. Transfer your equity to a third party
Since the latest revision of the Companies Law, the transfer of equity to an outsider was simplified. You no longer need to obtain consent from half of the remaining shareholders. Instead, you must send a written notice that states the price, terms, and transfer conditions. The other shareholders have a pre-emptive right to purchase the shares on the same terms within 30 days. If they do not exercise that right, you can sell to your chosen buyer. The articles of association can impose additional rules, as long as they do not make a transfer impossible. This change makes it easier for a foreign investor to find a buyer.
2. Company buy-back and ‘tag-along/drag-along’ rights
Sometimes your partner does not want a third party coming in. You can, therefore, agree on buy-back triggers – for instance, if one shareholder breaches a non-compete clause, the other has the right to force that shareholder to sell its stake to the company. Be careful: company buy-back is possible only under specific conditions listed in the Companies Law, and it must not impair the company’s ability to pay its debts. In practice, buy-backs usually happen by reducing registered capital, which takes time and involves creditor notices. A simpler path is a direct purchase between the founders, so a set of ‘tag-along’ (minority can sell together with the majority) and ‘drag-along’ (majority can force minority to join in a sale) protections is standard in a well-written JV agreement.
3. Dissolution and liquidation as a last resort
If the business fails or the relationship cannot be repaired, you can dissolve the company. The grounds include expiry of the company term, something listed in the articles of association, a resolution of the shareholders’ meeting, or a court judgment when corporate management is deadlocked and the continuation would cause serious losses. A liquidation committee is formed, at least one director or independent accountant is appointed, and after official announcements to creditors the company eventually deregisters. In a solvent company, the remaining assets after debt repayment are distributed to shareholders in proportion to their paid-in capital.
A Few Sample Clauses – Just to Get You Thinking
The following are abbreviated examples to show the style and do not constitute legal advice. Always ask a Chinese-licensed lawyer to review them in the context of your deal.
Pre-emptive rights on transfer
‘If any shareholder (the ‘Selling Shareholder’) intends to transfer all or part of its equity in the Company to a third party, it shall give written notice to the other Shareholder at least thirty (30) days in advance, stating the volume of shares to be transferred, the price, the payment terms, and other material conditions. The other Shareholder has the right to purchase such shares on the same terms and conditions. If the other Shareholder fails to notify the Selling Shareholder of its decision within thirty (30) days from receipt of the notice, the Selling Shareholder may transfer such equity to the third party on terms no less favorable than those stated.’
Dividend distribution clause
‘Subject to applicable laws and regulations, the net profit for each fiscal year, after taxation, after making up accumulated losses and after accumulating a reserve for non-recurrent expenses, may be distributed to Shareholders according to their paid-in capital proportion, unless all Shareholders agree in writing to a different distribution plan for that fiscal year.’
Deadlock exit trigger
‘If the shareholders’ meeting and the board of directors fail, after three consecutive meetings, to reach a decision on a significant business matter (as defined in Annex A), or if no board meeting can be validly held, any Shareholder may serve a written Notice of Deadlock on the other. The other Shareholder may, within thirty (30) days, elect to buy all shares of the party issuing the notice at a price determined by an independent valuer on the basis of net asset value. If the other Shareholder does not so elect, the party issuing the deadlock notice has the option to buy the other Shareholder’s shares on the same valuation basis.’
Do Your Homework Before You Sign
Daniel’s confusion is normal. Chinese corporate law now resembles a modern global framework, but the difference is in the details: how the negative list is applied in his city, how the registration authority processes foreign ownership records, and how the tax bureau treats his particular home-country treaty. A competent local lawyer, plus an experienced accountant, will be worth the fee.
Start the discussion at forum.chinacomes.com