

Emma, a product designer from Manchester, has worked in Shanghai for six years. She already has employer-provided social insurance for basic public hospital visits, but a small cycling accident last autumn made her wonder what would happen if she needed expensive care. At an international clinic, she paid about ¥1,200 out of pocket for a consultation and several stitches. When she asked local colleagues what insurance they buy, she heard three recurring terms: “high-end medical,” “million-pay medical” and “critical illness.” This article explains these three types in plain English and helps you weigh your own options.
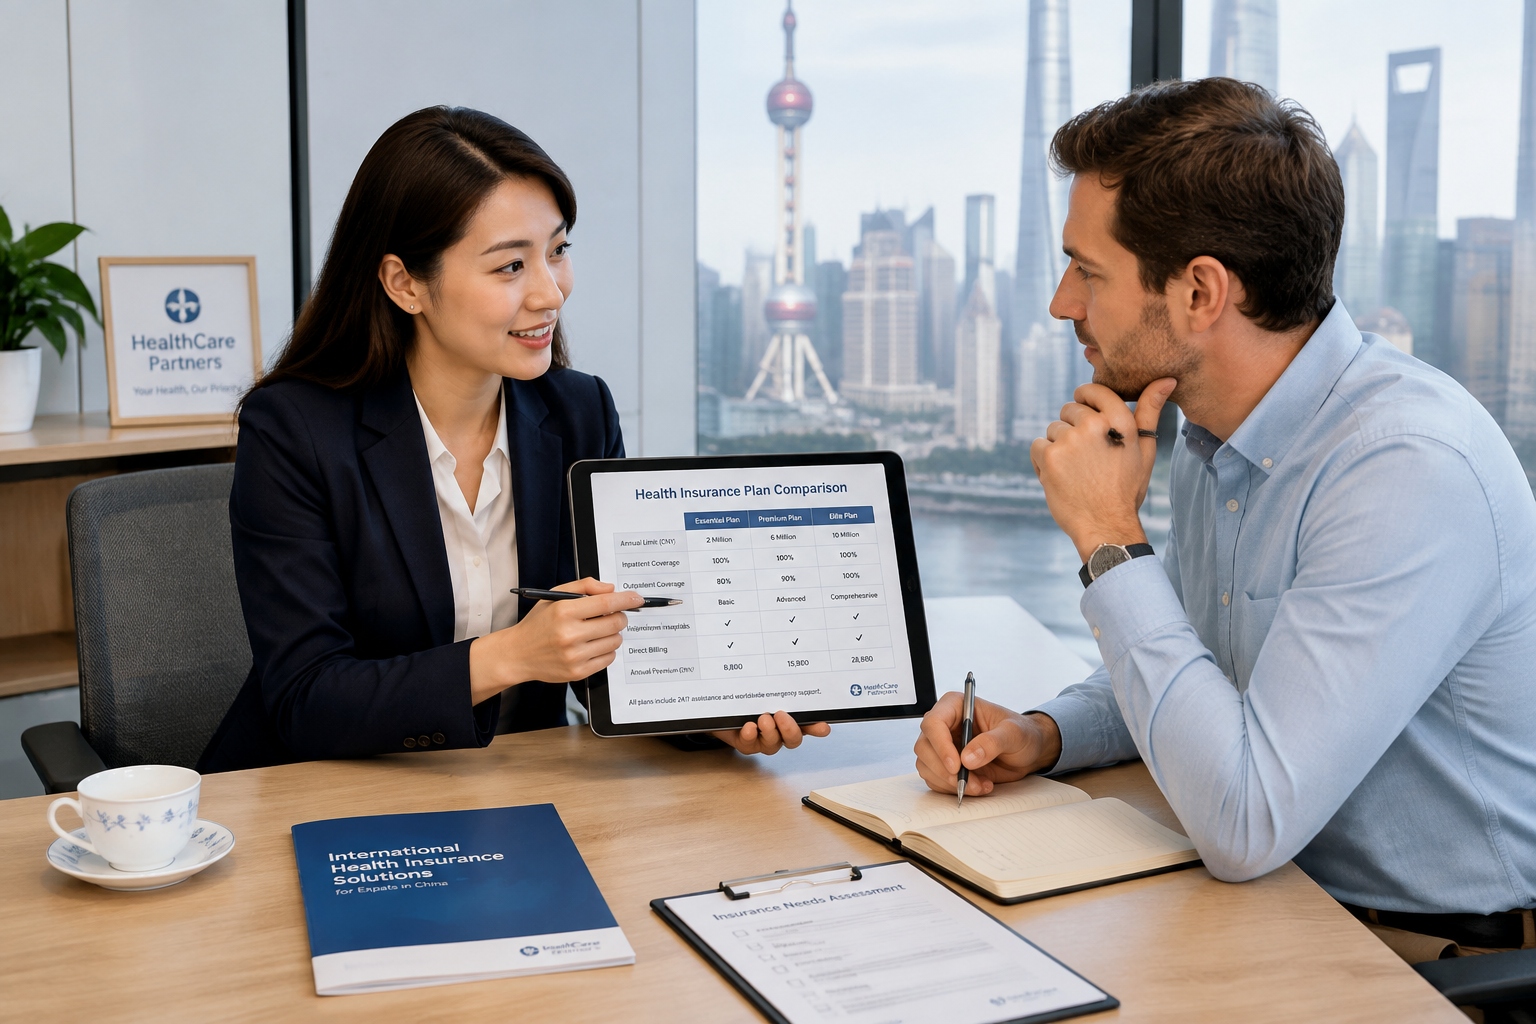
The three categories at a glance
Commercial health insurance in China has grown rapidly. Instead of trying to replicate one magic product, the market has separated three functions. High-end medical insurance mainly expands your choice of hospitals and lowers the hassle of reimbursement. Million-pay medical insurance gives you low-cost protection against very large hospital bills. Critical illness insurance gives you immediate cash when a serious disease is diagnosed, regardless of what you actually spend.
High-end medical insurance: pay for convenience and global access
High-end medical insurance is the broadest form of private health coverage in China. It covers outpatient, inpatient and often dental, maternity, vaccinations and alternative treatments at a network that includes private hospitals (for example, United Family, ParkwayHealth, and many boutique clinics), international departments of public hospitals, and — if you buy a “worldwide” tier — hospitals abroad.
For a healthy 35-year-old non-smoker in Shanghai, a mainland-China-only plan with a small deductible might cost around ¥15,000–¥30,000 per year. A comprehensive worldwide plan, covering the US and Europe, may start above ¥40,000 and reach ¥100,000. Those numbers scare some people, but a policy with real international benefits at this price is often cheaper than a similar package in New York or London. The key advantage is direct billing: you show your insurance card and the clinic sends the bill to the insurer. No need to save receipts for a heavily prolonged reimbursement process.
Another benefit is customisation. Carriers allow you to adjust the deductible to lower the premium, and you can add riders such as outpatient, maternity or molecular disease screening. Read carefully whether the policy is guaranteed renewable, because some “high-end” plans are still annual contracts and may be cancelled at renewal.
Million-pay medical insurance: a cheap insurance against expensive stays
“Million-pay medical” (百万医疗险) is the product that exploded on Chinese internet platforms. It does one thing well: it insures you against hospital bills of six figures or more. A healthy 30-year-old might pay between ¥300 and ¥800 per year for a plan with an annual limit of ¥2 million. The reason it is cheap is the ¥10,000 per-year deductible and the restriction to standard wards in public hospitals. Outpatient visits are not covered, and you pay for the first ¥10,000 of eligible inpatient costs yourself. Above that, the insurer picks up the rest up to the policy’s limit.
Such a plan is strictly for catastrophic illness or injury, not for routine comfort. But for most people, it is the most accessible source of true medical risk insurance. Avoid older one-year policies that can be discontinued. Since the regulator allowed “long-term” products, you can buy plans with a 6-, 10- or 20-year renewal guarantee. Look for the clause that specifies how the premium can increase before the renewal period ends.
Critical illness insurance: a lump sum when a doctor names your disease
Do not confuse critical illness insurance with medical insurance. Critical illness pays a fixed amount after you have been diagnosed with a condition that meets the exact medical definitions in your contract — for example, cancer, stroke, heart surgery or major organ transplant. The insurer does not need your hospital receipts; it simply pays you the policy amount in one go.
That cash is meant to replace income. While medical insurance covers the cost of doctors and drugs, the lump sum can cover rent or mortgage, childcare, a family member who comes to support you, rehabilitation expenses and the gap in salary during treatment. You decide how the money is used.
Premiums are higher than million-pay plans. A 35-year-old healthy male buying ¥500,000 of coverage for a 20-year term might pay between ¥6,000 and ¥12,000 per year, depending on how many conditions are covered and whether early-stage disease clauses are included. Older buyers pay much more, so it is wise to start early.
Side-by-side comparison
The table below summarises the main differences for a typical 35-year-old applicant.
| High-end medical | Million-pay medical | Critical illness | |
|---|---|---|---|
| Core benefit | Reimburses healthcare bills and provides premium service | Reimburses unusually large hospital bills | Pays you fixed cash on diagnosis |
| Typical annual premium | ¥15,000–¥100,000+ | ¥300–¥1,500 | ¥5,000–¥15,000 per ¥500,000 cover |
| Deductible | Often none, or ¥0–¥10,000 optional | Usually ¥10,000 per year | None, but must meet disease definition |
| Where you can be treated | Private/international hospitals, public VIP, overseas | Public hospital standard wards (some plans allow mixed categories) | No reimbursement restrictions — money is yours |
| Typical claim flow | Direct billing, no cash advance | File invoices after discharge | Wait for doctor’s pathology report, then receive cash |
| Renewal | Usually annual; choose if guaranteed | Annual to 20-year guaranteed terms available | Fixed term or lifetime premium schedule |
There is no single column that wins on all fronts. The one you pick depends on the specific uncertainty that worries you.
How to select what you actually need
Start by asking what would actually happen to your finances and access to care if you got a serious illness. Do you rely on your salary? Would waiting at a public hospital make you anxious? Do you want to be able to fly home for treatment?
Here is a decision guide based on typical expat situations:
- If you cannot afford a loss of savings, buy a million-pay plan with a long-term renewal guarantee. This is your baseline against ruin.
- If your work doesn’t provide generous sick pay, add a critical illness plan, especially if you are the sole earner in your household.
- If you have young children or you simply value English-speaking doctors and short waits, a high-end medical plan may justify its cost. Many multinationals in China offer this as a perk; check with HR first.
You can also combine. A common local choice is a critical illness plan for the breadwinner plus a million-pay policy for everyone in the family, and a high-end medical policy if the budget allows. For a growing family, your agent can build a package; just make sure the product wording is read carefully, not just the brochure.
Finally, remember that private health insurance in China is separate from your state-owned social insurance, and it is legally available to foreigners with valid work and residency permits. The actual policy cost is not fixed because of age, smoking, existing conditions and the specific optional benefits. The article explains the category, but before you sign, ask the insurer for the full policy wording and let a licensed broker confirm which product fits.
Editor’s note: Premiums and product terms change as insurers update their plans. Figures above are general ranges from the market in 2025 and should not be treated as offers. This guide only gives an educational framework and does not constitute personalised insurance or legal advice.
Start the discussion at forum.chinacomes.com